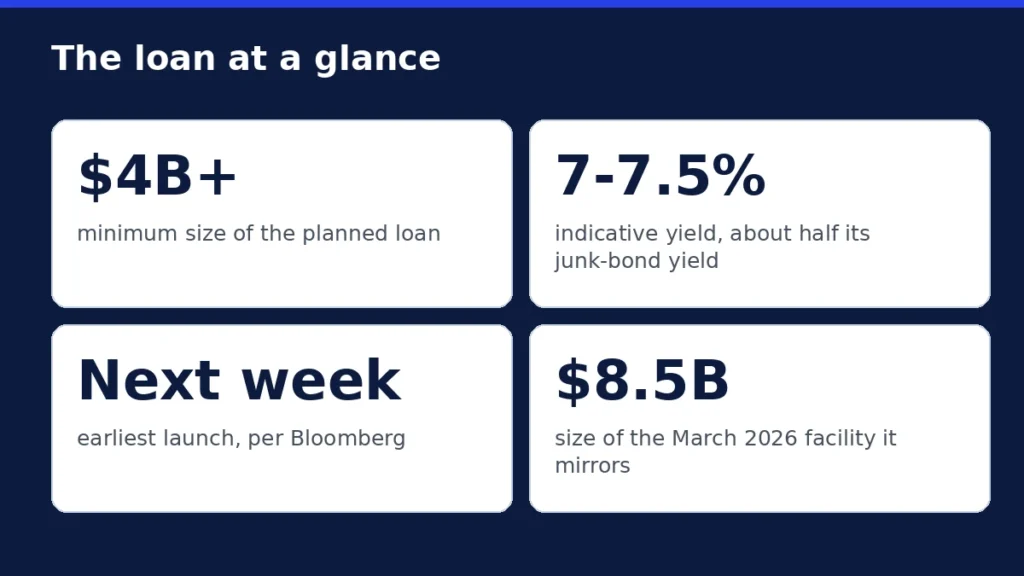
CoreWeave plans to raise at least $4 billion through an investment-grade loan, Bloomberg reported late Wednesday, in a deal that would let the AI cloud provider borrow more cheaply as it races to fund a massive data centre buildout. The loan could launch as soon as next week, according to people familiar with the matter cited by Bloomberg.
The facility would carry a yield of 7% to 7.5%, roughly half the yield on CoreWeave’s outstanding high-yield bonds, Bloomberg said. Morgan Stanley and Mitsubishi UFJ Financial Group are leading the deal, which is expected to be distributed in stages. The terms are preliminary and could still change before launch.
The loan is the latest step in a funding push that has defined CoreWeave’s year. The company, which rents out Nvidia-powered computing capacity to AI labs and enterprises, has to keep borrowing to pay for data centres and chips faster than its revenue arrives. An investment-grade loan, priced off the strength of customer contracts and the equipment itself, would be a cheaper way to do that than the junk-rated debt it has relied on so far.
A strong quarter, and a heavy bill
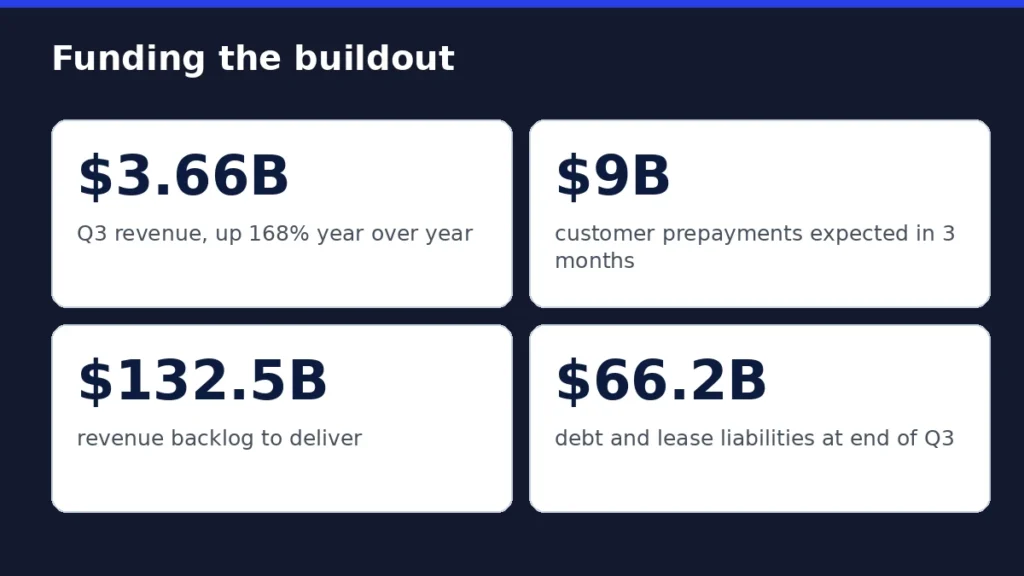
The financing plan follows a third quarter that beat expectations. CoreWeave reported revenue of $3.66 billion for the three months ended September 30, up from $1.37 billion a year earlier, a jump of 168%. Shares rose 24.7% on Wednesday after the results, according to the Associated Press.
The company also told investors it expects about $9 billion in customer prepayments and deposits over the next three months, a figure it disclosed alongside the results and which points to demand still running ahead of supply. Its order backlog stood at $132.5 billion at the end of the quarter.
But the growth comes with a heavy bill. CoreWeave guided to capital spending of $35 billion to $39 billion for fiscal 2026, and its debt and lease liabilities reached $66.2 billion at the end of the third quarter, up from $51.6 billion at the end of June, according to Dealroom. In the third quarter alone it raised about $4.2 billion through convertible bonds and set up a program to sell up to 35 million shares of Class A stock.
How the new loan would work
The proposed facility links computing equipment with customer commitments, a structure similar to an $8.5 billion financing arrangement CoreWeave completed in March 2026. Chip-backed loans of this kind typically cover 70% to 100% of equipment cost, depending on the customer, Dealroom reported, and are tied to a specific investment-grade customer contract.
CoreWeave chief executive Michael Intrator said on the earnings call that 75% of the company’s committed capital spending for 2027 is tied to investment-grade and enterprise customers, and that it expects less than $5 billion of new parent-level capital through 2027. The message to investors was that the borrowing is increasingly secured against real contracts and real hardware, rather than the company’s own balance sheet.
Credit markets have been watching closely. Reuters has reported that the yield on CoreWeave’s bonds maturing in 2031 exceeded 16%, a level associated with distressed debt, and credit default swap prices have implied a roughly 63% probability of default within five years. An investment-grade facility priced at 7% to 7.5% would be a marked improvement on those terms, if it closes as reported.
Why it matters
CoreWeave is one of the largest of the so-called neoclouds, the specialist providers that buy Nvidia GPUs in bulk and rent them to AI companies. Its ability to keep raising money on workable terms matters well beyond its own balance sheet: it is a test of whether the AI infrastructure boom can keep financing itself as spending scales into the tens of billions per quarter.
The timing also matters for Nvidia. CoreWeave is a major buyer of its chips, and the CoreWeave investment-grade loan is expected to fund further purchases. If the deal launches next week as Bloomberg reported, it would be the company’s second large equipment-backed financing this year, and a signal that lenders are willing to fund the AI buildout at investment-grade prices when the debt is tied to contracted demand.
For now the deal is planned, not done. The amount, the yield and the other terms are all preliminary, and Bloomberg noted they could change before launch. Investors will be watching whether the facility prices where reported, and whether it opens the door to more investment-grade borrowing for a company that has so far lived on costlier debt.
Sources
- Bloomberg News (via TradingView and Reuters), “CoreWeave plans to raise at least $4 billion in high-grade loan”
- Crypto Briefing, “CoreWeave seeks $4B investment-grade loan to boost financial stability”
- EL7.AI (citing Bloomberg and Investing.com), “CoreWeave Targets at Least $4 Billion in Investment-Grade Loan”
- Dealroom, “CoreWeave plans multibillion-dollar chip-backed debt deal”
- MarketWatch, “Here’s how CoreWeave is funding its AI buildout”
- GPTOnline, “CoreWeave Turns to Customer Prepayments and Shorter Contracts to Fund AI Growth”
- GPTOnline, “CoreWeave Q3 Revenue Jumps 168% to $3.66 Billion as Backlog Hits $132.5 Billion”